What is the scope and industry significance of the Centerpull Towel Refill Market?
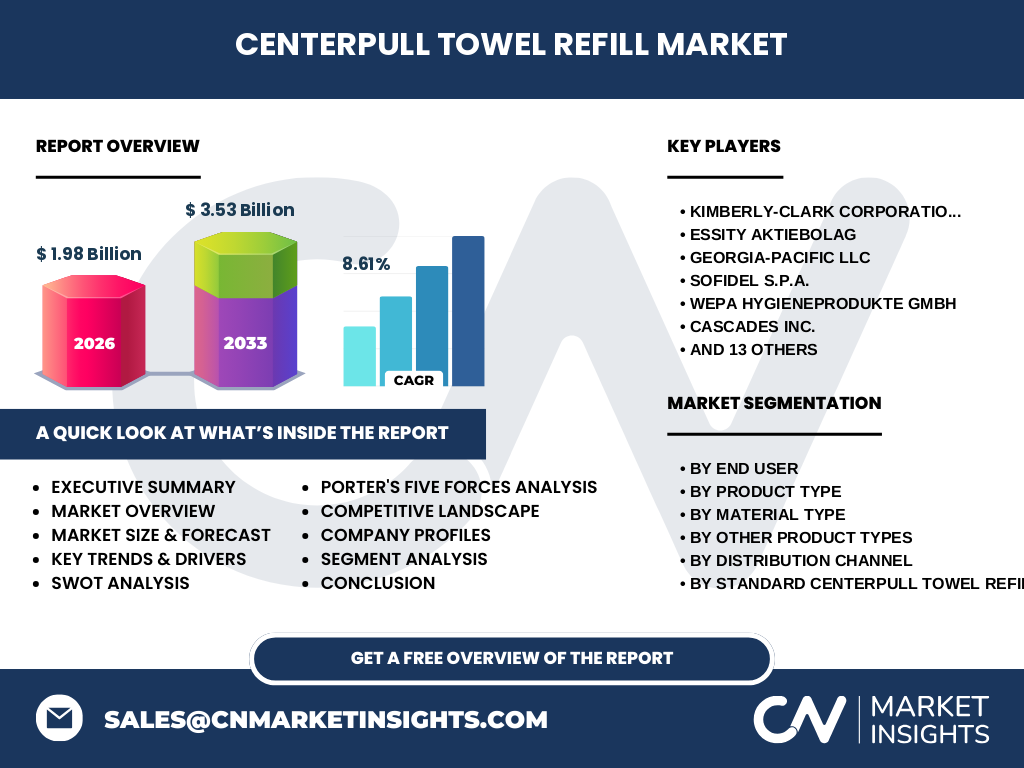
The Centerpull Towel Refill Market reaches a valuation of 1.98 Billion in 2026, driven by rising hygiene demands across commercial sectors. Our analysis indicates that specialized dispensing formats reduce cross-contamination risks in high-traffic washrooms, cementing their role in institutional sanitation infrastructure.
Key market drivers, restraints, challenges, and opportunities shaping Centerpull Towel Refill Market
Growth is propelled by stringent OSHA and EPA sanitation standards, though raw material price volatility for virgin pulp remains a key restraint. Industry players leverage eco-friendly alternatives to capitalize on corporate sustainability mandates, turning supply chain logistics into competitive advantages.
Emerging trends and growth patterns in Centerpull Towel Refill Market
The shift toward sustainable hygiene solutions highlights bamboo fiber and compostable variants as dominant growth patterns. Consumer preference for touchless dispensing systems has accelerated demand for high-capacity jumbo rolls across metropolitan commercial spaces.
COVID-19 impact analysis and recovery trajectory
The pandemic permanently altered institutional hygiene protocols, generating an immediate surge in demand for single-sheet dispensing refills. The recovery trajectory reflects sustained institutional spending on infection control, anchoring long-term sector stability.
Competitive landscape and strategic market dynamics
Market concentration remains moderate to high, featuring heavyweights like Kimberly-Clark Corporation and Georgia-Pacific LLC dominating global supply chains. Strategic positioning centers on vertical integration and proprietary dispenser lock-in models to secure recurring refill revenues.
Executive summary of the Centerpull Towel Refill Market
Valued at 1.98 Billion in 2026, the market is projected to expand significantly to reach 3.53 Billion by 2033 at a robust CAGR of 8.61%. This trajectory underscores the critical intersection of institutional hygiene compliance and sustainable material innovation.
Market forecast from 2027 to 2033
Expanding from 2027 through 2033, the market will scale up to 3.53 Billion, translating to a strong CAGR of 8.61%. Accelerated adoption in healthcare and food service sectors will primarily fuel this expansion phase.
Segmentation analysis across end-users and product types
Market segmentation is categorized by end-user (Healthcare, Food Service, Hospitality, Manufacturing, Education, Other End Users) and product type (Standard, High Capacity, Eco Friendly, Other). Each segment addresses specific institutional consumption rates and regulatory compliance needs.
Regional market analysis and geographic distribution
Geographic performance highlights North America and Europe as mature revenue centers, while Asia-Pacific emerges as the fastest-growing region. Urbanization and expanding commercial real estate drive robust adoption across developing economies.
In-depth regional review of key markets
North American growth is anchored by stringent FDA and HACCP guidelines in food service facilities. Meanwhile, European markets prioritize circular economy mandates, heavily favoring recycled paper and compostable bamboo fiber refills.
Company profiles and strategic positioning of leading firms
Industry leaders such as Essity Aktiebolag, Sofidel S.p.A., and Cascades Inc. focus on expanding their eco-certified product portfolios. Regional specialists like Morcon Tissue Corporation and Kruger Products L.P. leverage localized distribution networks to capture niche institutional accounts.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to consolidated pulp markets, while buyer power is high among large facility management conglomerates. Threat of substitution is mitigated by proprietary dispenser compatibility, protecting manufacturer margins.
SWOT analysis of the Centerpull Towel Refill Market
Strengths include high product necessity and recurring consumption models, offset by weaknesses in bulk shipping logistics costs. Opportunities abound in biodegradable materials, though environmental compliance regulations pose persistent operational threats.
Value chain analysis from raw materials to end-users
The value chain flows from forestry and agricultural raw material sourcing through high-speed manufacturing conversion to B2B distribution networks. Logistics optimization via key maritime ports and regional hubs remains vital for maintaining margin integrity.
Investment insights and high-potential growth areas
High-potential investment targets include closed-loop recycling technologies and bamboo fiber conversion plants. Investors should prioritize manufacturers with strong ESG credentials and diversified distribution channels spanning online and traditional B2B platforms.
Conclusion and key takeaways for stakeholders
Reaching 3.53 Billion by 2033, the market offers lucrative opportunities for agile manufacturers embracing sustainability. Stakeholders must align product development with stringent institutional hygiene and environmental regulations to secure market share.
Research methodology for baseline estimations
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with procurement directors, and secondary macroeconomic indicators from global hygiene associations.
Scope of the report and coverage parameters
This report covers global revenue projections from 2027 to 2033, analyzing segmentation across materials, product types, and distribution channels. Limitations include localized currency fluctuations and unrecorded informal institutional channels.
Recent developments, partnerships, and strategic moves
Recent industry moves highlight Metsä Tissue Oyj and WEPA Hygieneprodukte GmbH investing in fossil-free production mills. Strategic M&A activity continues as major players acquire regional converters to optimize supply chain resilience.